Adult Daughters Take a Larger Role in Family Financial Planning
- Cargo
- Investing
- Shipped
- Shipper
- Christopher Williams
- Readers
- 599
Advisors at the Women Advisor Summit stressed trust and financial confidence as adult daughters become more involved in family planning.
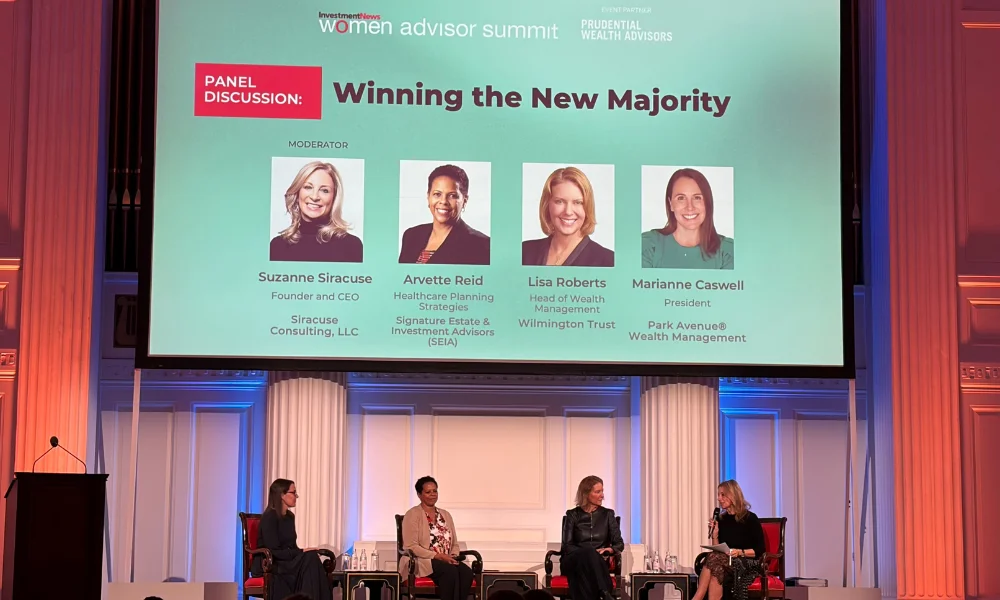
Adult daughters are becoming an important part of financial planning conversations, especially when families are addressing the needs of aging parents and preparing for wealth to pass to the next generation. At the Women Advisor Summit in New York City, advisors described those conversations as a way to build trust, support women’s confidence and strengthen relationships across a family.
Arvette Reid, healthcare planning strategist at Signature Estate & Investment Advisors, said adult daughters often carry responsibility for understanding and coordinating their parents’ financial needs. They come to advisors with questions and want reassurance that they’re making sound decisions, she said. Starting a conversation with daughters and daughters-in-law, Reid added, helps establish trust before families face more complex planning needs.
That work can also widen an advisor’s connection beyond the person who has traditionally led the client relationship. Suzanne Siracuse, founder and CEO of Suzanne Siracuse Consulting and creator of the summit concept more than 10 years ago, said advisors need relationships with heirs and other members of the next generation as well as with primary clients.
Siracuse pointed to planning conversations as a practical way to bring family members into open discussion. If a female client isn’t participating in meetings as much as she would like, an advisor can use a planning conversation to create space for her involvement, she said. The result can be a more complete view of family priorities and a stronger basis for communication among parents and children.
Longer lives add weight to family planning
The need for those conversations is growing alongside the older population. In 2020, one in six people in the United States was 65 or older, according to the U.S. Census. The population in that age group reached 55.8 million between 2010 and 2020, an increase of 38.6%. The Census described that decade’s growth as the fastest for the 65-and-over population since 1880 to 1890.
Longer lifespans can mean families have to coordinate care, financial resources and decision-making over an extended period. Adult children may be asked to help parents assess options or manage practical details, while also handling their own household finances. For advisors, that makes it useful to identify who is involved in those responsibilities and what each person needs to understand. The panel discussion highlighted trust and clear communication as parts of that work.
Women’s financial role and confidence don’t always align
Women’s growing role in household decisions was another focus at the summit. Marianne Caswell, president of Park Avenue Wealth Management, cited CFP Board data showing that 69% of women are the primary financial decision-makers in their households. She cautioned advisors against assuming that women clients share a single set of priorities or a common financial profile.
Decision-making responsibility does not necessarily come with confidence. Caswell said just under a third of women report feeling financially confident. Research released earlier this year by Beacon Pointe Advisors found that 31% of women feel highly confident managing their finances. A 2022 study from the Global Financial Literacy Excellence Center reported that 30% of women worldwide are financially literate, compared with 35% of men.
Those figures describe different measures: reported confidence in managing finances and financial literacy. Together, they point to a gap advisors may encounter between clients’ responsibilities and their comfort with financial decisions. Caswell said advisors can help by building clients’ confidence. That requires understanding the person across the table, listening to her concerns and explaining decisions in a way that supports informed participation.
Lisa Roberts, head of wealth management at Wilmington Trust, framed intergenerational planning as a relationship change as well as a transfer of assets. Advisors who focus only on the movement of wealth risk overlooking the connections and expectations that shape how families approach it, she said. Roberts urged women advisors to invest in those relationships, describing them as a source of client confidence.
Relationships are part of the planning work
The panel’s message was that family planning reaches beyond account balances and future transfers. When daughters are included early, advisors can learn how families communicate, who is taking responsibility and where clients need more clarity. Those discussions can also give the next generation a chance to ask questions before a major family transition makes decisions more immediate.
There’s no single approach for every household. Caswell’s warning against assumptions is relevant across generations: clients differ in their experience, confidence and role in family decisions. Advisors who make room for those differences can build a clearer picture of what each person understands and what support they need.
The Women Advisor Summit brought together more than 20 speakers for more than 10 content sessions on Nov. 5 at 583 Park Avenue on Manhattan’s Upper East Side. The event concluded with the Women to Watch Awards, which recognize influential women in wealth management. The summit’s emphasis on adult daughters reflects a broader planning challenge: as families live longer and financial decisions shift among generations, trust and communication can shape how well clients navigate the change.


